

Daily Loan - Money Tracker
by SUMMIT CITY PROSTHETICS & ORTHOTICS, INC.
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
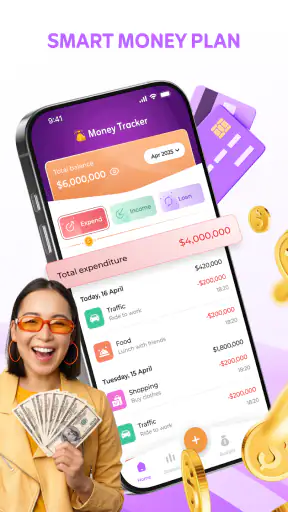
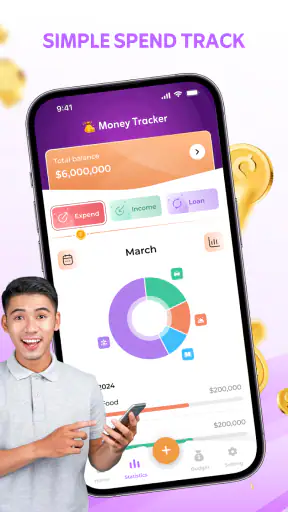
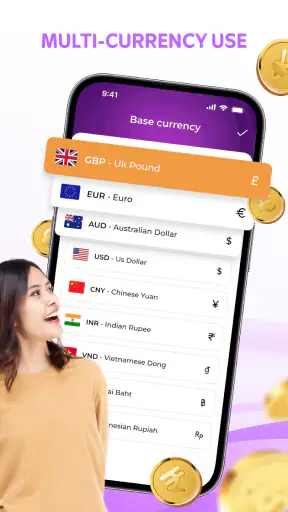
Managing money sounds simple until small purchases begin to blur together. A coffee, a taxi ride, a subscription renewal, and a repayment can all look harmless on their own, yet the total can quietly change the shape of a month. Daily Loan - Money Tracker takes a deliberately narrow approach to that problem: it is a finance app built around recording expenses, watching budgets, and keeping loan-related activity visible. After spending time with it, I found its appeal less about novelty and more about whether I would still open it when the first-week curiosity had disappeared.
The answer depends heavily on what you want from a money tool. If you need a lightweight place to enter spending and keep an eye on limits, it can be a sensible companion. If you expect a full banking dashboard, automatic account connections, investment analysis, or elaborate financial planning, this is not the kind of app I would choose. Its store summary presents it as a way to track expenses and manage budgets, while its short description is simply “Daily Loan,” so I approached it as a focused tracker rather than a complete personal-finance system.
What the first week feels like
The strongest part of the first week is the clarity that comes from recording purchases close to the moment they happen. I found that a tracker becomes useful when it interrupts the vague feeling of “I have probably spent too much” and replaces it with a running view of where money is actually going. That is especially helpful for irregular everyday spending, which is easy to underestimate when it is scattered across several days.
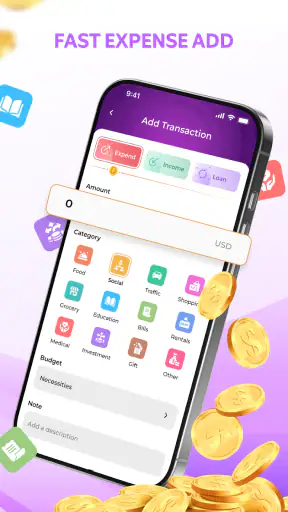
I would begin with a small, realistic routine rather than trying to rebuild my entire financial history. Entering current expenses gives the budget a clean starting point and makes the app’s purpose easier to judge. Backfilling every old transaction can create unnecessary work and may make the first session feel like bookkeeping. For a new user, the better test is whether recording today’s spending feels quick enough to repeat tomorrow.
A practical example is a week in which I buy lunch away from home, pay for transport, make a household purchase, and send money toward a loan. None of those actions is unusual, but they belong to different parts of my financial life. Separating them helps me see whether the problem is one large bill or a pattern of small choices. That distinction is more useful than simply seeing one reduced bank balance.
The app’s free price lowers the barrier to trying this routine, and its Everyone content rating makes it approachable for a broad audience. It is also available for devices running Android 7.0 or later, which means people using older compatible phones may still be able to consider it. I would still judge the experience by how comfortably it fits into daily behavior, because a free tracker that I stop using has no practical value.
During the opening days, the most important decision is how detailed to be. Recording every purchase with excessive precision can make the habit feel like a chore. On the other hand, entering only broad totals may hide the categories that need attention. I prefer a middle path: capture the amount and the meaningful spending type, then add detail only when it will change a decision. The goal is not to create an accounting archive; it is to make the next spending choice easier.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Useful for a simple starting point
Daily Loan - Money Tracker is a good fit for someone who has never maintained a budget and wants a direct way to begin. A person saving for a short-term goal, trying to control discretionary spending, or keeping an eye on repayments can gain more from consistent entries than from a complicated financial suite that feels intimidating. The app’s straightforward positioning works in its favor here.
I also see value for people whose finances are split between several payment methods. When spending happens through cash, a card, and occasional transfers, memory becomes unreliable. A manual tracker can act as a single personal record, provided I am willing to enter transactions consistently. That last condition matters: the app cannot make an unrecorded purchase visible by itself.
The first-week test should therefore include a missed entry. If I forget to record something, can I add it later without losing the thread of the budget? That is a more realistic test than entering five perfect transactions in a row. Real financial habits include busy evenings, rushed commutes, and receipts that stay in a pocket until the next day.
Why it can remain useful month after month
The long-term value of a budget tracker comes from comparison. One isolated day tells me very little, but several weeks can reveal recurring pressure points. I might discover that a budget is not failing because of one dramatic purchase; it may be strained by frequent convenience spending, poorly timed bills, or repayments that were never given their own space. A tool like this earns a lasting place when it helps turn those observations into a repeatable monthly decision.
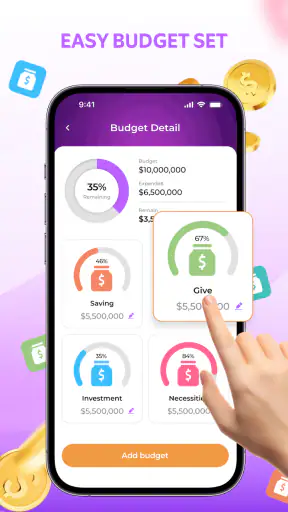
My preferred monthly workflow would be to set a spending intention at the beginning of the period, record transactions as they occur, and review the result before the next cycle begins. The review should be short and practical. Which category exceeded its limit? Which expense was predictable but forgotten? Which amount should be protected before flexible spending begins? These questions give the tracker a job beyond displaying numbers.
That workflow also exposes an important trade-off. Manual entry gives me control over what is recorded and how it is interpreted, but it demands attention. Automatic financial apps reduce that effort by importing activity, yet they can require account connections, deal with duplicate transactions, or classify purchases incorrectly. I would choose Daily Loan - Money Tracker over an automated alternative when privacy of routine matters more to me than convenience, or when I want to record cash spending that a bank feed would never see.
For someone with several accounts, investments, shared household finances, or complex recurring obligations, the balance may shift toward a broader finance platform. A focused tracker can still complement those tools, but I would not rely on it as the only place for a complicated financial picture. Its lasting strength is concentration: it encourages attention to expenses and budgets instead of trying to become every kind of money service at once.
A better way to use the budget view
One non-obvious habit is to treat a budget as an early-warning system rather than a scorecard. If I wait until the end of the month to see that a limit was exceeded, the information arrives too late. Checking the position after a few days of normal spending lets me adjust while the decision is still reversible. I might delay a nonessential purchase, move money between flexible categories, or simply recognize that the original limit was unrealistic.
Another useful approach is to create a distinction between predictable and flexible expenses in my own routine, even if I keep the entries simple. A loan repayment, utility bill, or regular commitment should not compete mentally with an optional meal or impulse purchase. When those obligations are visible early, the remaining budget becomes more honest. This is particularly relevant to an app whose short store description centers on daily loans: repayment awareness should be part of the routine, not something checked only after money becomes tight.
I would also avoid changing the budget every time a difficult week appears. A budget needs enough stability to reveal patterns. If I constantly move limits to make the numbers look comfortable, the tracker becomes a diary of excuses rather than a planning tool. Adjustments are appropriate when circumstances change, but they should follow a review of actual behavior, not replace it.
The maintenance cost nobody notices at installation
The main burden here is not learning the interface; it is remembering to use it. A money tracker can feel excellent during setup and still disappear from daily life because each transaction requires a deliberate action. That maintenance cost is small when I make an entry immediately, but it grows when I postpone several purchases and then try to reconstruct them from memory.
I would attach the habit to an existing moment, such as checking a receipt, arriving home, or reviewing the day before bed. The exact trigger matters less than its consistency. Entering expenses in batches can work for disciplined users, but it introduces uncertainty when purchases are forgotten or amounts are rounded. My preference is immediate entry for unusual spending and a short daily review for everything else.
There is also a mental cost to categorization. Too many categories make the record look precise while making the process tiring. Too few categories make the monthly review less actionable. I would start with categories that lead to decisions—food, transport, household needs, repayments, and flexible purchases—then add another only when an existing group is hiding a meaningful pattern.
The current version is 1.0.6, and the app was released on January 21, 2026. Those details place it relatively early in its public life, so I would keep expectations measured about how deeply refined its long-term workflow may feel. That does not make it unsuitable, but it does reinforce my advice to judge the everyday routine rather than assuming that a large feature set will grow around it.
Its developer is SUMMIT CITY PROSTHETICS & ORTHOTICS, INC., an unusual name for a finance product. I would not treat the developer name alone as a reason to reject the app, but I would be more deliberate about checking that the app behaves as expected on my device and that it fits my comfort level before making it the central record of my finances. A money tool deserves a little more caution than a casual utility because the information entered can be personally sensitive.
When maintenance becomes worthwhile
The routine pays off when the information changes what I do. If I record every expense but never review the result, I am performing administration without gaining guidance. I would schedule a brief weekly check, not to obsess over every purchase, but to identify one action for the coming days. That could be limiting a category, reserving money for a repayment, or changing a spending assumption before it causes trouble.
For couples or families, the app is less obviously convenient if several people need to update one shared picture. A single-person tracker is easier to maintain because responsibility is clear. If shared budgeting requires simultaneous access, permissions, or automatic synchronization, I would look for a service designed specifically around collaboration instead of forcing this app into that role.
Where fatigue can set in
The first source of fatigue is repetition. Recording routine purchases can feel pointless when the amounts are small, especially during a month that seems financially stable. The answer is to remember why those entries matter: repeated small expenses are often the exact pattern a budget is meant to reveal. Still, I would not pretend the task is effortless. Users who dislike manual tracking may abandon it even if the budgeting idea is sound.
The second source is incomplete context. A transaction amount can tell me what left my pocket, but not necessarily whether it was planned, shared, refundable, or connected to a future obligation. I can add my own notes or use a consistent naming habit where the app allows it, but a simple tracker will not replace a full financial journal. That is acceptable for basic budgeting, yet limiting for users who need detailed records for work, taxes, reimbursements, or household reconciliation.
The third is the danger of false confidence. Seeing a remaining budget can feel reassuring, but it may not represent money that is genuinely available if upcoming bills or repayments have not been entered. I would always review commitments before treating the remaining amount as spending money. This is one of the most important practical cautions: a tracker is only as complete as the financial picture I give it.
There is also a trade-off between speed and accuracy. If I stop to classify every purchase perfectly, the habit becomes slow. If I enter everything quickly without checking, the monthly picture may be misleading. The best compromise is consistent rules. I would decide in advance how to handle refunds, shared purchases, cash withdrawals, and transfers, then apply those rules the same way each time. Consistency makes trends more useful than occasional precision.
People looking for automatic bank synchronization, investment monitoring, credit-score tools, bill negotiation, or advanced forecasting should probably skip this app and choose a broader alternative. Those features can be valuable when finances are complex. Daily Loan - Money Tracker makes more sense for someone who wants a focused manual record and is comfortable taking responsibility for keeping it current.
Does it earn a permanent place?
The public response is encouraging: the app carries a 4.5 average from around 7.4 thousand ratings and has passed one million installs. Those figures suggest that the basic idea resonates with a substantial audience, although popularity does not remove the need to test whether the workflow suits my own habits. I would interpret that reception as a reason to try it, not as proof that it will replace every other finance tool.
For me, the lasting test is simple. After the first month, can I point to a decision that became easier because I had recorded the information? If the answer is yes, the app has recurring value. It can help make loan repayments visible, expose spending leaks, and give a modest budget a clear structure without charging an entry fee. If the answer is no, continuing to enter transactions becomes routine for its own sake.
I would recommend Daily Loan - Money Tracker to a person who wants a straightforward expense and budget habit, especially someone who prefers manual control and does not need a connected financial dashboard. It is also a reasonable starting point for people who find larger finance apps overwhelming. The free price and broad age rating make experimentation easy, while the focused purpose keeps the learning curve manageable.
I would not recommend it as the sole financial system for a household with complicated shared accounts, a business owner needing formal records, or an investor seeking portfolio insight. Those users would benefit more from specialized tools, even if they keep this app for quick personal spending notes. The right choice depends less on how many functions an app claims to have and more on whether its daily demands match the way I actually handle money.
My final view is positive but practical. The app does not earn permanent space because it makes budgeting exciting; it earns that space only when its small recording habit produces better monthly choices. If I keep the categories sensible, enter transactions before memory fades, and review the budget with a specific action in mind, it can remain useful well after the novelty disappears. If I resist manual maintenance or need automatic financial intelligence, I would move on. For the right user, that honesty is its strongest feature: it offers a focused tool, but it still expects me to participate.
Pros
- Simple interface for tracking daily loan payments and balances.
- Useful reminders can help users avoid missing repayment dates.
- Quickly records borrowed and lent money in one place.
- Clear transaction history makes outstanding amounts easier to review.
- Lightweight design should run smoothly on most modern phones.
Cons
- May lack advanced budgeting and financial analysis tools.
- Data accuracy depends on users entering every transaction correctly.
- Loan tracking may not support complex interest or repayment plans.
- Privacy policies and data handling should be checked before adding finances.
- Some useful features may require ads, registration, or in-app purchases.
FAQs for Daily Loan - Money Tracker
What is Daily Loan - Money Tracker used for?
Daily Loan - Money Tracker is designed to help users organize and monitor personal borrowing and repayment information in one place. You can record loan amounts, payment dates, outstanding balances, and related notes, making it easier to follow daily financial obligations. It is primarily a tracking tool, not a replacement for professional financial advice or a lending service.
Can Daily Loan - Money Tracker help me get a loan or provide money?
No. Daily Loan - Money Tracker should not be confused with a bank, lender, or cash advance provider. Its main purpose is to help you keep track of loans, debts, and repayment activity. The app does not automatically approve applications, guarantee funding, or remove the need to meet a lender’s eligibility requirements. Always verify any financial offer independently before sharing personal information or accepting terms.
Is my financial information safe when using the app?
Before entering sensitive details, users should review the app’s privacy policy, permissions, and data-handling practices in the relevant app store. Avoid recording passwords, full banking credentials, card security codes, or unnecessary identity information in notes. Device security also matters, so use a screen lock and keep the operating system updated. Data protection features may vary by version and platform.
Does Daily Loan - Money Tracker calculate interest, fees, or repayment schedules?
The app may provide tools for recording and organizing repayment details, but users should carefully check which calculations are actually supported in the installed version. Interest, late fees, lender charges, and payment rules can differ significantly between agreements. Treat any displayed estimate as a convenience rather than an official statement, and compare it with your contract or lender-provided repayment schedule.
Is Daily Loan - Money Tracker free to download, and are there extra costs?
The download price, advertising model, subscriptions, and optional in-app purchases can change depending on the Android or iOS store, country, and app version. Check the listing before installing and review the purchase screen carefully if premium features are offered. Using the tracker itself does not cancel debt or prevent lender charges, so continue making payments according to your original agreement.

Daily Loan - Money Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hannouch.said@gmail.com, visit https://budgettracker431cy14.netlify.app/, or review their https://budgettracker431cy14.netlify.app/policy.










